Institutional access to tokenized assets, a decision framework
By Jeremy Ryan, Founder & CEO · October 2026
Institutional access to tokenized assets is not simply a question of whether an organization can open a wallet and purchase a blockchain-based instrument. The real decision is broader: how an institution obtains economic exposure, verifies legal rights, controls transfers, manages custody, settles transactions, services the asset, and exits the position when needed.
For decision makers, the distinction matters. A token can move in seconds while the legal ownership record, cash settlement, collateral agreement, and fund administration process remain unresolved. Blockchain rails can improve parts of the lifecycle, but they do not automatically replace the controls that make institutional markets work.
• Institutional Access Is A Lifecycle, Not A Wallet
• Choosing The Right Access Route And Control Model
Institutional Access Is A Lifecycle, Not A Wallet
Institutional access to tokenized assets means an organization can obtain, hold, transfer, pledge, value, report on, and redeem a blockchain-based financial claim within its legal, operational, and risk-management framework. That definition includes direct token ownership, but it also includes indirect access through registered funds, exchange-traded products, managed accounts, notes, and other intermediated vehicles.
This is where many tokenization discussions become too narrow. A treasury team may seek exposure to tokenized short-duration government securities without wanting direct control of private keys. A fund manager may want a tokenized private-credit position but require administrator-approved valuations and transfer-agent records. A clearing or collateral team may care less about investment exposure than whether a tokenized security can be pledged, released, and reused inside a controlled workflow.
The institution is not buying “blockchain” as an abstract capability. It is choosing an operating arrangement for a specific asset and use case.
Separate Economic Exposure From Direct Token Ownership
An institution can gain economic exposure to tokenized assets without directly holding tokens. This distinction should be the first branch in an investment or infrastructure decision.
Direct ownership generally means the institution, its qualified custodian, or a delegated wallet operator controls the blockchain address holding the token. The organization must then govern signing authority, wallet recovery, address screening, transaction approval, accounting treatment, and interaction with the issuer’s transfer restrictions.
Indirect ownership places an intermediary between the institution and the token. A registered vehicle, fund, or note may hold tokenized instruments while the institution owns shares or interests in that vehicle. The investor receives economic exposure, but the manager, custodian, or issuer handles on-chain operations.
EY’s institutional survey found that 81% of respondents preferred spot digital-asset exposure through a registered vehicle, while 63% reported being very interested in tokenized assets. The combination suggests that demand for the asset class does not necessarily equal demand for direct wallet ownership. See EY’s Institutional Investor Digital Assets Survey for the underlying survey evidence and reported barriers.
| Access Route | Who Controls The Token Or Vehicle | Best Fit | Main Trade-Off |
|---|---|---|---|
| Direct token ownership | Institution or appointed custodian | Organizations needing settlement, collateral, or programmable rights | Higher operational and control burden |
| Custodian-operated access | Qualified custodian controls keys under mandate | Institutions requiring direct ownership with delegated operations | Provider dependency and fee structure |
| Registered vehicle | Fund, issuer, or sponsor holds underlying tokens | Investors seeking exposure without blockchain operations | Less control over settlement and token utility |
| Managed account or note | Manager or issuer controls implementation | Institutions testing allocation or accessing specialized strategies | Counterparty and structural complexity |
I would not assume direct ownership is inherently more advanced. It is appropriate when the token itself provides operational value: same-day collateral movement, controlled settlement, programmable distribution rules, or participation in a permissioned market. It may be unnecessary when the objective is simply portfolio exposure.
Test Legal Enforceability Before Technical Capability
A token’s existence on a blockchain does not, by itself, establish enforceable ownership of an underlying bond, fund interest, real estate interest, or private-credit claim. Institutions should treat legal enforceability as a separate diligence gate from technical validation.
The core question is simple: what legal right does the token holder have, against whom, and under which governing documents? The answer may depend on an issuer, special-purpose vehicle, trustee, fund administrator, transfer agent, or custodian. In some structures, the token is the authoritative ownership record. In others, it is a controlled representation of a record maintained elsewhere. In still others, it may represent a contractual claim rather than direct title.
Before allocation, verify these points:
The offering documents define the token holder’s rights, redemption terms, restrictions, and priority in an insolvency scenario.
The official ownership record is identified, including whether the blockchain ledger, transfer agent register, or another record controls in the event of a mismatch.
The issuer can enforce transfer restrictions and can process exceptions such as court orders, lost credentials, sanctions screening, or an incorrect transfer.
The redemption process connects the token to the underlying asset, cash proceeds, or fund interest without relying on informal manual intervention.
Consider a tokenized fund unit that appears transferable on a public blockchain. If only whitelisted investors may own it, the transaction is not truly complete merely because the wallet-to-wallet transfer confirms. The fund administrator must recognize the transferee, the transfer agent must update the holder record where required, and the investor must remain eligible under the governing documents. The blockchain transaction may be technically final while the legal and administrative process is not.
That gap is manageable, but only if it is explicit in the design.
Distinguish Technical T+0 From Full Institutional Finality
Tokenization can support atomic settlement designs, meaning the asset leg and cash leg either complete together or fail together. CoinPaprika’s explanation of tokenized-asset custody describes on-chain atomic settlement as a potential route to T+0 execution when both transaction legs settle simultaneously.
That is useful, but it is only one layer of finality.
For institutional purposes, a transaction may also need legal title transfer, final settlement of the payment leg, sanctions and eligibility checks, reconciliation to books and records, exception processing, and post-trade reporting. A blockchain confirmation answers whether a network accepted a transaction. It does not automatically answer whether every legal and operational obligation has been discharged.
Treat on-chain confirmation as an event in the settlement process, not as proof that every institutional obligation has been completed.
This is particularly important when cash remains off-chain or when a tokenized asset depends on a transfer agent, fund administrator, or securities depository. The practical benefit of blockchain settlement comes from reducing handoffs and reconciliation breaks, not from declaring every transaction final at the moment a block is produced.
Choosing The Right Access Route And Control Model
The strongest institutional designs start with the use case, then select the access route, network model, custody arrangement, and servicing model required to support it. Starting with a preferred chain or vendor reverses the decision order.
Compare Providers By Control Layers
A useful evaluation method is to map who controls each layer of the transaction. This exposes hidden dependencies that are easy to miss when a provider offers a polished tokenization interface.
| Control Layer | Decision Question | Why It Matters |
|---|---|---|
| Issuance | Who creates, burns, or replaces tokens? | Determines supply integrity and remediation authority |
| Eligibility | Who approves investors and wallet addresses? | Determines whether transfers remain compliant |
| Custody | Who controls private keys and recovery procedures? | Determines asset protection and operational resilience |
| Asset Record | Which ledger controls legal ownership? | Determines enforceability in a dispute |
| Settlement | What constitutes completed delivery versus payment? | Determines counterparty and liquidity risk |
| Redemption | Who converts tokens into cash or underlying assets? | Determines exit certainty |
| Servicing | Who performs valuation, income processing, tax, and reporting? | Determines whether the instrument can fit institutional operations |
A public blockchain may offer broad technical reach and more potential interoperability. A permissioned network can embed identity controls and participant restrictions at the network level. A bank-operated platform may fit more naturally into existing settlement, custody, and reporting channels. None is universally superior.
Choose a public-chain model when external composability, broad distribution, or interoperability with established token ecosystems is material and asset-level controls can manage eligibility. Choose a permissioned or bank-operated environment when known counterparties, privacy, controlled access, and integration with existing institutional systems matter more than open transferability.
The decision should connect to blockchain platform selection for financial institutions, especially where participant eligibility, resilience, transaction privacy, and governance need to be assessed together. (enterprise blockchain architecture in regulated industries)
Evaluate Liquidity At The Asset And Venue Level
A token can be transferable without being liquid. This is one of the most important reality checks in institutional access to tokenized assets.
Liquidity depends on more than blockchain uptime. It depends on eligible buyers and sellers, market makers, transfer restrictions, valuation confidence, financing availability, settlement certainty, and the legal ability to move the asset between venues. A tokenized Treasury may have a robust underlying market but limited liquidity in its specific token format. A tokenized private-credit instrument may have an active issuance channel but no practical secondary market at all.
EY reported that 38% of surveyed respondents cited insufficient secondary liquidity as a hurdle to tokenized-asset adoption. That figure does not measure market-wide liquidity, but it does capture a persistent institutional concern: technical transferability should not be confused with dependable exit capacity.
For each proposed instrument, ask:
• Is there a verified secondary venue, or only a theoretical ability to transfer?
• Which investors are eligible to buy the token?
• Are market makers committed, and under what conditions?
• Can the token move to another custodian or trading venue without forced redemption?
• How are prices determined when the underlying asset does not trade continuously?
• What happens if the issuer pauses transfers, the network is unavailable, or a required compliance check fails?
A practical test is to model an exit before buying. If a $20 million position must be reduced during a stressed period, identify the counterparties, settlement mechanism, valuation source, approval path, and expected timeline. If those answers rely on a future marketplace that has not yet demonstrated depth, liquidity should be treated as uncertain.
Design For Collateral, Servicing, And Failure Recovery
The most credible institutional tokenization use cases often focus on controlled workflows rather than broad retail distribution. Collateral mobility is a strong example. A tokenized security can potentially be pledged, transferred, released, and reused with less manual reconciliation if legal agreements, valuations, custody controls, and margin processes are aligned.
BitGo’s account of DTCC-related tokenized-securities infrastructure describes tokenized Treasuries and equities being used in custody, transfer, repo, reverse-repo, collateral pledging, and settlement workflows. The significance is not that every tokenized security is immediately repo-ready. It is that the institutional value proposition becomes clearer when a token can participate in existing balance-sheet and collateral processes.
A collateral workflow should be rejected or redesigned if it cannot answer four operational questions:
How is the asset valued for margin purposes, and who resolves a valuation dispute?
Can the secured party obtain control promptly after a default or margin call?
Does the legal documentation recognize the tokenized representation and applicable custody arrangement?
Can the asset be released, substituted, or transferred across the relevant network and custodian boundaries?
Institutions also need failure recovery. Interoperability problems are often described broadly, but the actual failure modes are concrete.
| Failure Mode | Potential Effect | Recovery Design |
|---|---|---|
| Network outage | Transfers and collateral movements pause | Defined fallback timing, emergency procedures, and reconciliation queue |
| Unsupported wallet standard | Asset cannot move to intended custodian or venue | Preapproved wallet compatibility testing before trade execution |
| Mismatched identity rules | Eligible investor rejected by another venue | Shared or mapped identity and whitelisting policies |
| Fragmented liquidity | Position cannot be exited efficiently | Venue-specific limits and prearranged liquidity support |
| Record mismatch | Blockchain balance conflicts with legal register | Clear authoritative record and exception-resolution process |
Institutional custody should be designed as governance, not merely key storage. Blockchain Council’s institutional custody overview describes common controls including segregation, approval workflows, whitelisting, reconciliation, and use of qualified custodians or regulated banks where applicable. Those controls matter because the organization must demonstrate who can authorize a transfer, under what policy, and how that decision can be reconstructed later.
The operating model should define ownership across legal, compliance, treasury, investment, technology, finance, and operations teams. For organizations building that structure, creating an enterprise blockchain operating model is a useful starting point for assigning decision rights and escalation paths.
Key Takeaways
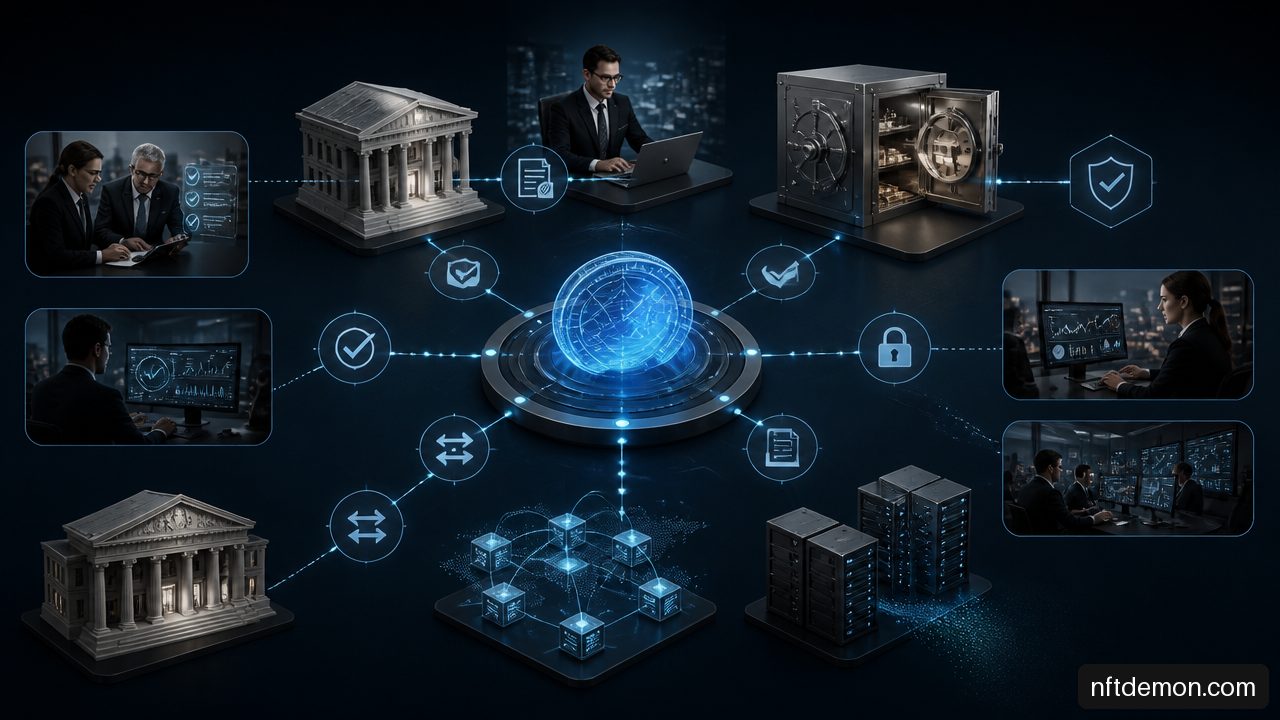
• Institutional access is a full lifecycle. It includes eligibility, acquisition, custody, transfer controls, settlement, valuation, servicing, redemption, reporting, and recovery.
• Economic exposure and direct token ownership are different decisions. Registered vehicles may be preferable when an institution wants exposure but does not need token-level functionality.
• Legal rights require separate validation. A blockchain record should be tied clearly to enforceable claims, authoritative ownership records, and a defined redemption process.
• T+0 is not a complete answer. Atomic on-chain delivery can reduce settlement risk, but legal title, payment finality, reconciliation, and exceptions still require institutional design.
• Liquidity must be assessed asset by asset and venue by venue. A technically transferable token can remain difficult to sell, finance, or use as collateral.
• Collateral is a practical institutional test case. The token must be controllable, valued, legally recognized, and transferable under stress.
• Architecture follows the use case. Public, permissioned, and bank-operated networks each create different trade-offs around eligibility, privacy, integration, and interoperability.
Frequently Asked Questions
What Does Institutional Access To Tokenized Assets Actually Mean?
It means an institution can access a tokenized security or real-world asset through a structure compatible with its investment mandate, compliance obligations, custody policy, accounting process, and operating model. Access can be direct through a wallet and custodian, or indirect through a registered fund, note, or other investment vehicle.
Can An Institution Gain Exposure Without Holding Tokens Directly?
Yes. An institution can invest through registered vehicles, managed products, funds, or notes that hold or reference tokenized assets. This route can reduce wallet-management and settlement complexity, though it may also limit direct use of the token for collateral, transfer, or programmable workflows.
How Can An Institution Verify That A Token Represents A Real Asset?
Review the legal documents, issuer structure, transfer-agent or administrator role, custody arrangement, authoritative ownership record, audit or attestation practices where available, and redemption mechanics. The key question is not merely whether the token exists, but whether a holder can enforce the associated economic and legal claim.
Are Tokenized Assets Liquid Enough For Institutional Portfolios?
Some may be, but the answer depends on the asset, venue, investor eligibility rules, market makers, and exit process. Tokenized government securities may have stronger underlying liquidity than tokenized private assets, yet the specific token format can still have limited secondary-market depth. Institutions should test real exit mechanics before assigning liquidity assumptions.
Can Tokenized Securities Be Used As Collateral?
They can be structured for collateral use when custody, legal control, valuation, margining, settlement, and default procedures are aligned. A token alone is not enough. The secured party must be able to establish and enforce control over the asset within the relevant legal and operational framework.
Does Blockchain Settlement Provide True T+0 Finality?
Blockchain systems can support rapid or atomic transaction confirmation. Full institutional finality may take longer because it can require legal title recognition, cash settlement, compliance validation, reconciliation, and post-trade processing. The relevant question is which parts of the workflow actually become final at the time of the on-chain event.
Which Network Model Is Best For Institutional Tokenization?
Choose based on the use case. Public networks may suit broader interoperability and external distribution. Permissioned networks may suit controlled participant groups and embedded identity rules. Bank-operated platforms may suit organizations prioritizing integration with existing custody and settlement workflows. The best choice is the one that preserves legal control and operational continuity for the intended transaction.
Sources And References
• EY — Institutional Investor Digital Assets Survey: https://www.ey.com/en_us/financial-services/institutional-digital-assets-survey
• Citigroup — Citi Digital Assets: https://www.citigroup.com/global/about-us/strategy/digital-assets
• BitGo — Inside the Infrastructure Powering DTCC’s Tokenized Securities Milestone: https://www.bitgo.com/resources/blog/inside-the-infrastructure-powering-dtccs-tokenized-securities-milestone/
• CoinPaprika — How Custodians Are Adapting to Tokenized Assets: https://coinpaprika.com/education/how-custodians-are-adapting-to-tokenized-assets/
• Blockchain Council — Tokenized Asset Custody: Wallets and Trustees: https://www.blockchain-council.org/digital-assets/tokenized-asset-custody-wallets-trustees-institutional-custody/
NFT Demon Holdings helps enterprises scope, evaluate, and build blockchain programs — start with a free evaluation call.
Talk through your use case
Free evaluation call — objective, constraints, and fit, before any proposal.